Problem
A portfolio's volatility tells you about an average day. It says almost nothing about the day that actually hurts. For an equity-heavy book, the question a risk committee cares about isn't ‘how much does this bounce around’ — it's ‘how much could we lose on a genuinely bad day, and how much should we trust that number?’ This project compares three estimates of a downside loss threshold and examines how their assumptions affect the result.
Data
1,508 trading days of daily returns for an 8-asset portfolio, using adjusted-close prices from Yahoo Finance via yfinance over 2019–2024. The window spans the COVID crash and the 2022 rate-hike bear market.
Method
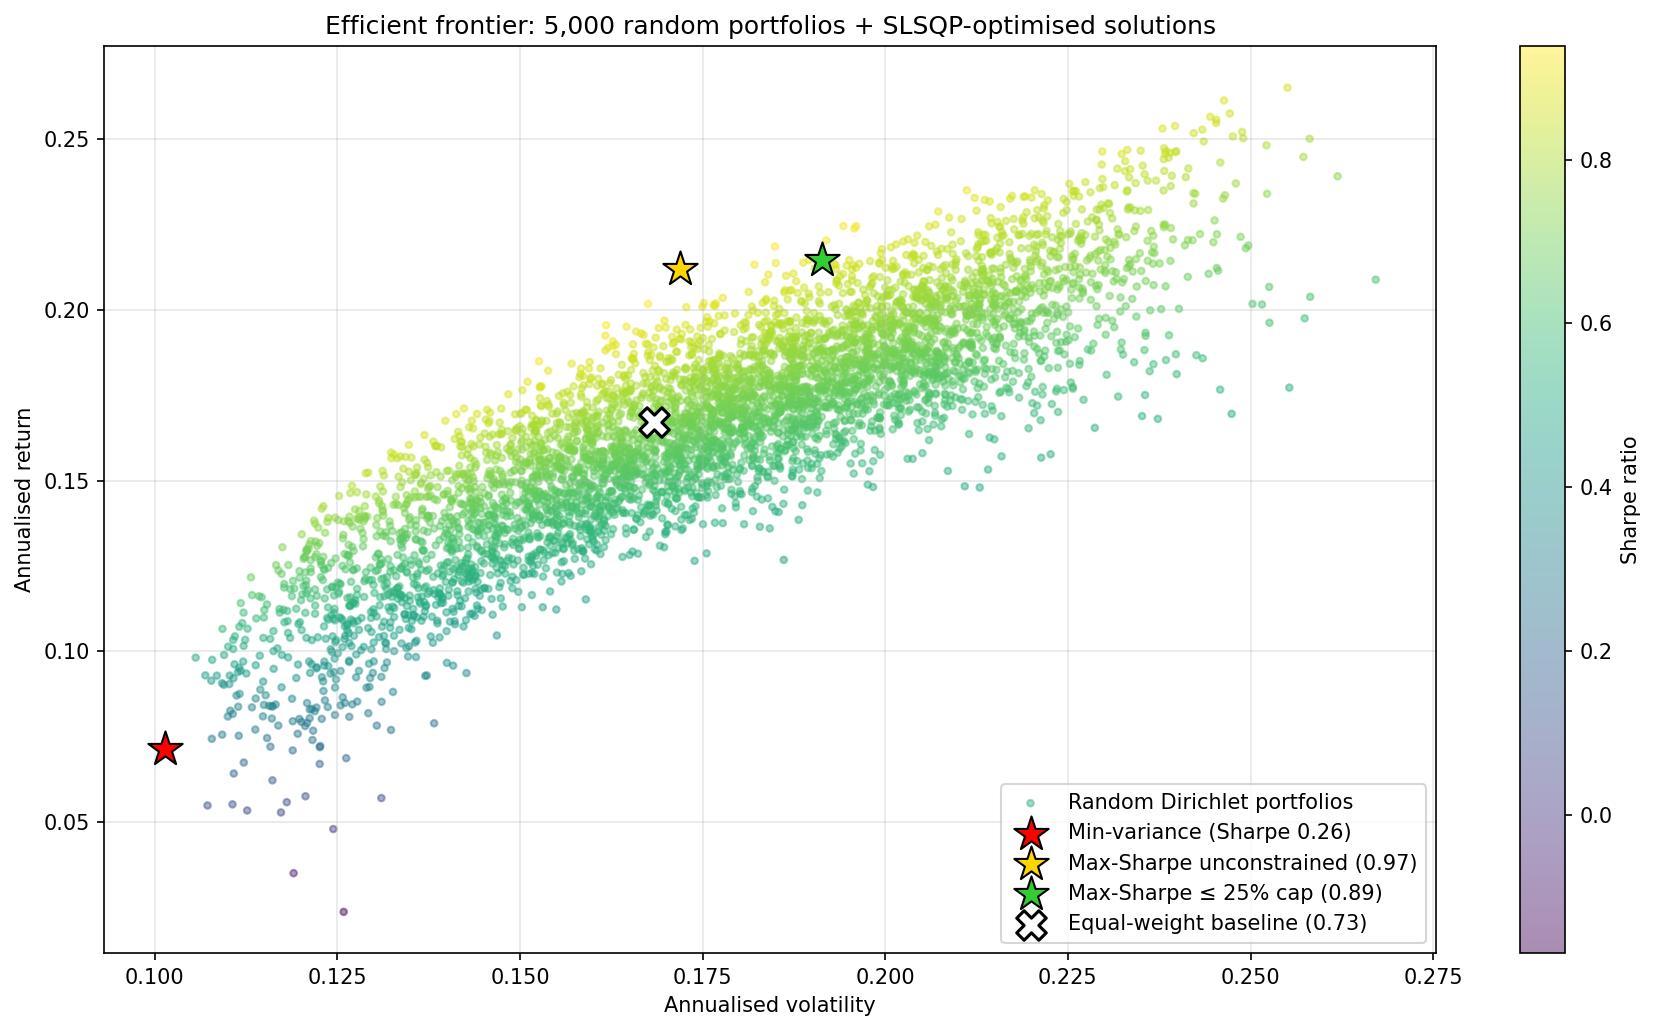
Three Value-at-Risk methodologies were implemented side by side: historical simulation (reading the loss straight from the 1st percentile of actual returns), parametric (assuming a normal distribution), and Monte Carlo (simulating thousands of correlated return paths via Cholesky decomposition). An efficient-frontier optimiser then swept thousands of weight combinations to map the risk/return trade-off.
Finding
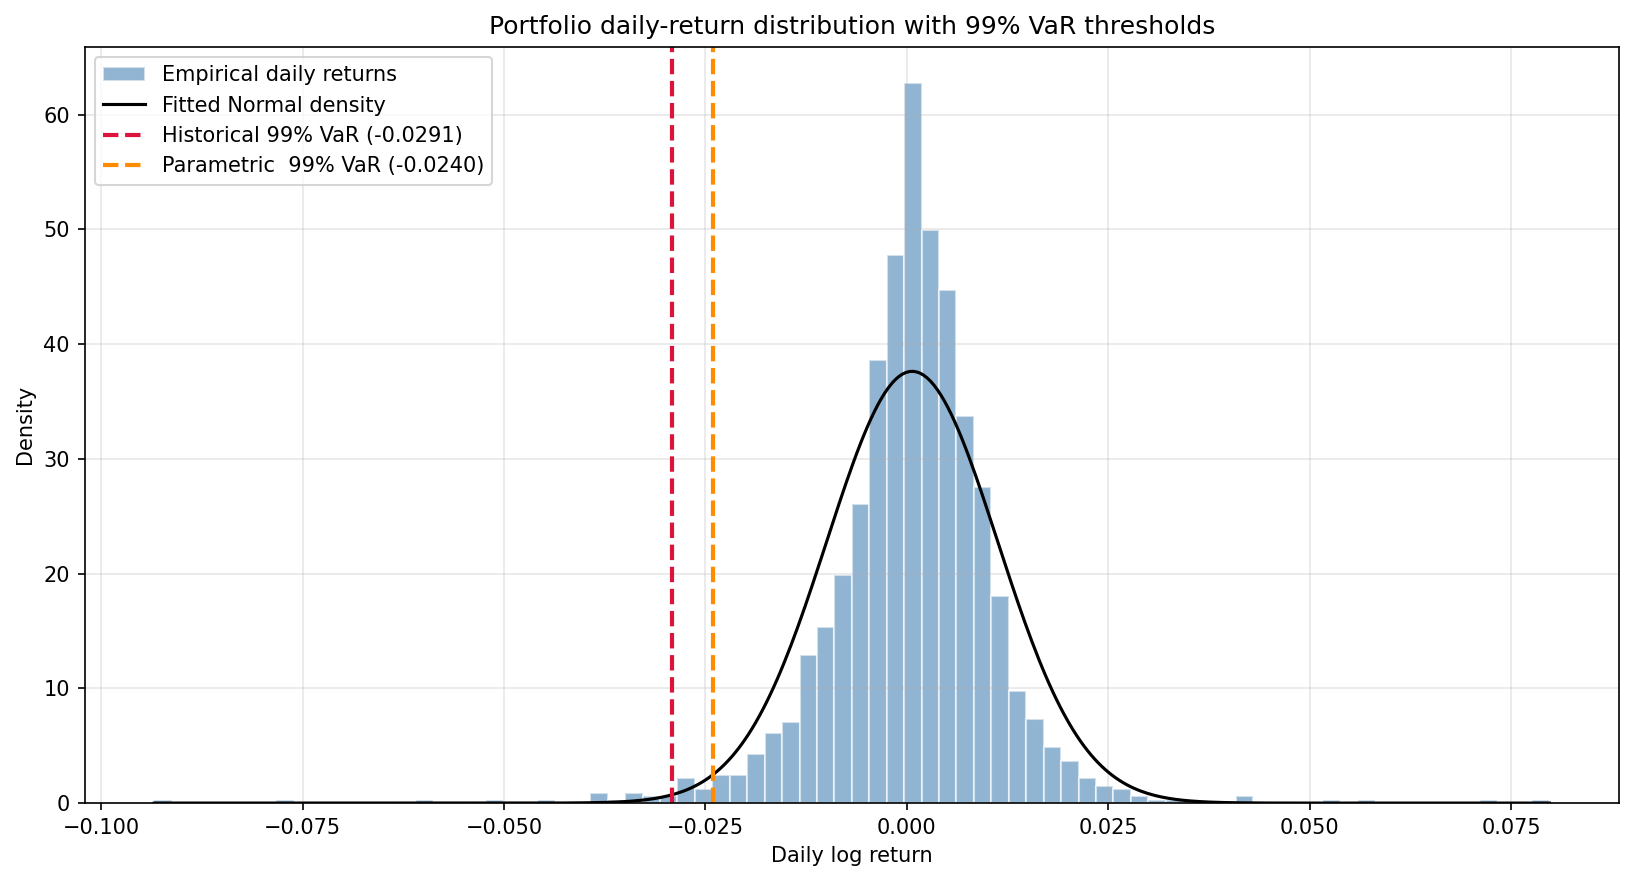
At 99% confidence, the historical 1-day VaR on a $1M portfolio is $29,146 — but the parametric model, trusting a normal distribution, put it roughly $5,100 lower.
That gap is the fat tail the normal curve can't see: the ‘safe’ assumption estimates the loss threshold about a sixth lower — precisely when the number matters most.
Recommendation
The project recommends a 70/30 blend of the equal-weight portfolio and the maximum-Sharpe allocation: Sharpe rises from 0.725 to 0.823 while 99% VaR remains essentially flat. In a separate comparison, adding gold and Treasury exposure to the six-equity portfolio reduces 99% VaR by about 25%, with lower annualised return. Evaluate these trade-offs across market regimes and after transaction costs before using either allocation.
Limitations and next steps
These estimates depend on the historical window, portfolio weights, and distribution assumptions. VaR is a loss threshold, not a maximum possible loss. Next steps are to backtest exceedances on later periods, compare expected shortfall, and include transaction costs in the rebalancing analysis.